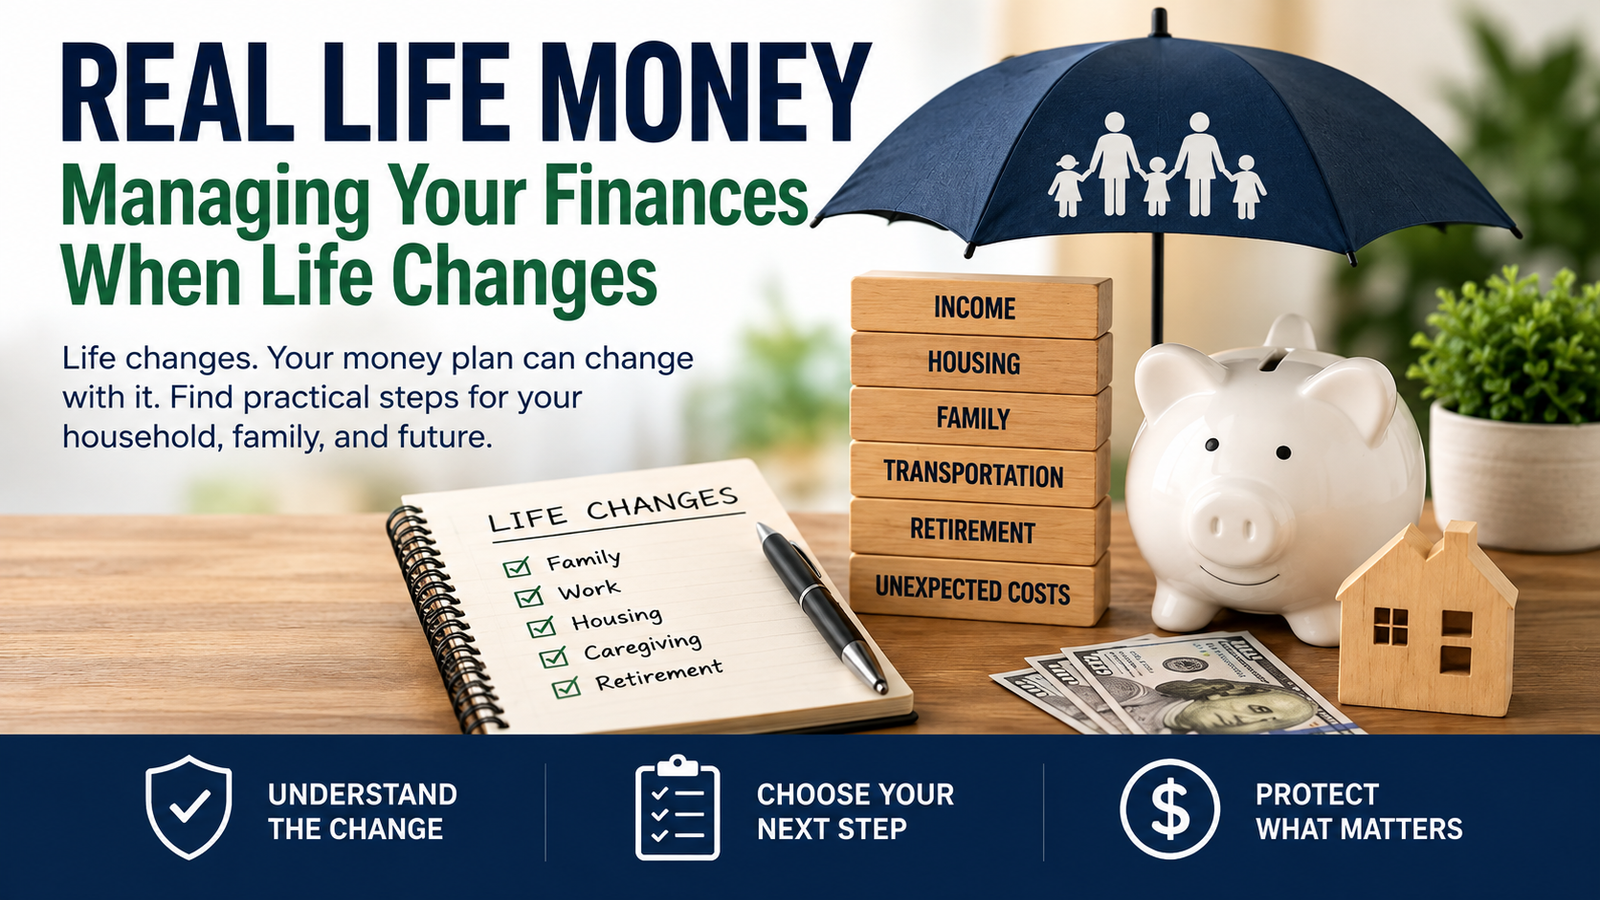
Real life money is what happens when your finances meet an ordinary Tuesday—or a change you never saw coming. A car needs replacing. Your household grows. A paycheck stops. Retirement arrives. The spending plan that worked last month may suddenly need a different set of numbers.
Some changes give you time to prepare. Others ask you to make decisions while you are tired, worried, or grieving. This guide helps you find the situation that fits, see what needs attention first, and reach the practical help elsewhere on this site. You do not have to solve everything today.
Real Life Money: Start With What Changed
Before choosing a solution, write down three things: what changed, what it does to your household income or expenses, and which decision has a deadline. A drop in income calls for different steps than a planned move. A bill due tomorrow needs more immediate attention than a purchase you can postpone.
- Income: Is money coming in lower, less predictable, or coming from a different source?
- Expenses: What new costs are essential, temporary, or optional?
- Responsibilities: Are you managing money for someone else, combining finances, or taking over tasks another person handled?
If you need a clearer starting picture, use the Money Checkup. Then choose the section below that matches your situation.
When Income Drops or Bills Become Difficult
When income drops, real life money decisions begin with the money available for the next few weeks and the bills due during that period. Protect housing, utilities, food, and essential transportation. Contact providers or creditors early to ask about available arrangements, and keep a note of what they tell you.
A side job may help some households, but it takes time and may bring costs of its own. Do not build an immediate bill-paying plan around income you have not received. First work out the shortfall and the deadline.
Read In a Financial Hardship? Find Real Help You Need Now for help options, or Unpaid Bills? Here’s How to Decide What to Pay First to sort competing bills. Once the immediate pressure is clearer, revise your numbers with How to Make a Budget.
Combining Finances or Raising a Family
Moving in together, getting married, or welcoming a child changes more than the grocery bill. These real life money changes call for a shared plan. Decide how you will share expenses, handle existing debt, and make larger purchases. You can agree on a household plan without using identical spending habits or merging every account.
For a growing family, price the costs you actually expect: childcare, insurance changes, time away from work, and everyday supplies. Separate one-time purchases from ongoing expenses. For example, a stroller is one purchase; childcare may become part of every month’s spending.
Start with Financial Planning for Couples and Money Communication in Relationships. If you manage a household on your own, Single Parent: Practical Money Saving Tips addresses that situation.
Housing Decisions: Buying, Staying, or Moving
Housing is one of the largest real life money decisions most households face. A housing decision needs a total-cost comparison. Beyond the mortgage or rent, include insurance, taxes where applicable, utilities, repairs, moving expenses, and transportation. A lower payment can come with higher costs elsewhere.
Write down why you are considering a change. Is the current home becoming expensive, difficult to maintain, or poorly suited to daily life? Compare the costs of staying with the costs of moving before making commitments. A move can improve the monthly picture while still requiring substantial money up front.
The Home in Retirement guide explores staying or moving as needs change. Downsizing in Retirement helps with belongings and the practical side of a move. Visit Money Tools to explore the mortgage and spending-plan calculators.
Transportation and the Cost of Getting Around
Transportation brings real life money choices into daily routines. It is both a money question and an independence question. When replacing a car, compare the payment with insurance, maintenance, registration, fuel, and parking. If driving becomes difficult or a driver is no longer available, work out how you will reach appointments, buy groceries, and stay connected.
Compare the cost of keeping a vehicle with the actual trips you need. Ask local services about availability and eligibility before counting on them. A ride that sounds affordable is not much help if it does not operate when you need it.
Read Buying a New Car? Don’t Overlook These Hidden Costs before purchasing. For changing driving needs, use Transportation in Retirement.
Medical Expenses and Helping Aging Parents
An illness can change household costs and the time available for paid work. The real life money task is to understand those changes without trying to solve every problem at once. List the financial tasks separately from care decisions: bills to review, insurance questions to ask, work benefits to check, and expenses that may continue. This keeps a difficult situation from becoming one enormous to-do list.
If a medical bill does not make sense, ask for an itemized explanation and compare it with the insurer’s explanation of benefits. Ask about financial assistance or payment arrangements before agreeing to terms you cannot manage.
When helping a parent, begin with their wishes and permission. Identify which tasks they want help with, who already assists them, and what arrangements exist for someone to act on their behalf. Avoid assuming that being family automatically gives you authority to manage an account.
Use How to Challenge and Negotiate a Medical Bill for billing questions. Managing Your Affairs in Retirement and Support Network in Retirement can help organize responsibilities. For signs of exploitation, read Elder Financial Abuse: What Every Family Needs to Know.
Retirement: When the Paycheck Pattern Changes
Retirement brings a new set of real life money questions: where income comes from, when it arrives, and which expenses continue. Begin with expected take-home income and essential spending. Then consider healthcare, housing, transportation, and the activities you want to afford. The goal is a plan that fits your life, not simply a savings figure.
If you are already retired, use the numbers you have now. When income or expenses change, review the affected parts of the plan rather than assuming every earlier decision was wrong.
Our Retirement & Real Life section offers separate paths for planning ahead, living in retirement, and responding when something changes. Money & Income in Retirement focuses on the income side.
When a Spouse or Partner Dies
Grief and financial paperwork are a difficult combination. Real life money guidance at this stage should help you take manageable steps. Begin with immediate household needs, payments coming due, and identifying the documents and contacts you will need. Ask someone you trust to help keep notes or organize calls if that would make the work manageable.
Avoid rushing major financial choices when they can wait. Some income, accounts, and benefits may change; confirm the details with the relevant organization rather than assuming everything continues as before.
When a Spouse Dies: Financial Steps for the Surviving Partner provides a focused place to begin. You can return here for help with housing, transportation, or other household changes as they arise.
A Simple Real Life Money Plan for the Next Week
- Name the change. Write one sentence describing the situation you need to handle.
- Update the numbers. List available income, essential costs, and near-term deadlines.
- Choose one action. Review a bill, ask about assistance, compare a cost, or gather a needed document.
- Choose a review date. Revisit what you learned and decide on the next step.
If an unexpected cost could push you into borrowing, the Emergency Fund guide explains how to build a cushion. For existing debt, visit How to Get Out of Debt and Stay Out for Good. These are supporting steps; your immediate situation determines where to begin.
For additional information, the Consumer Financial Protection Bureau’s consumer tools provide resources on household financial questions.
Make Real Life Money Work for Your Situation
You do not need to tackle every real life money question at once. Choose the change affecting your household, follow the relevant guide, and complete one practical step. Come back when you need help with the next decision.
If you want help building a regular routine around those decisions, try the free 7-Day Money Habits Challenge. Real life money gets more manageable when you have a way to notice changes and respond to them.