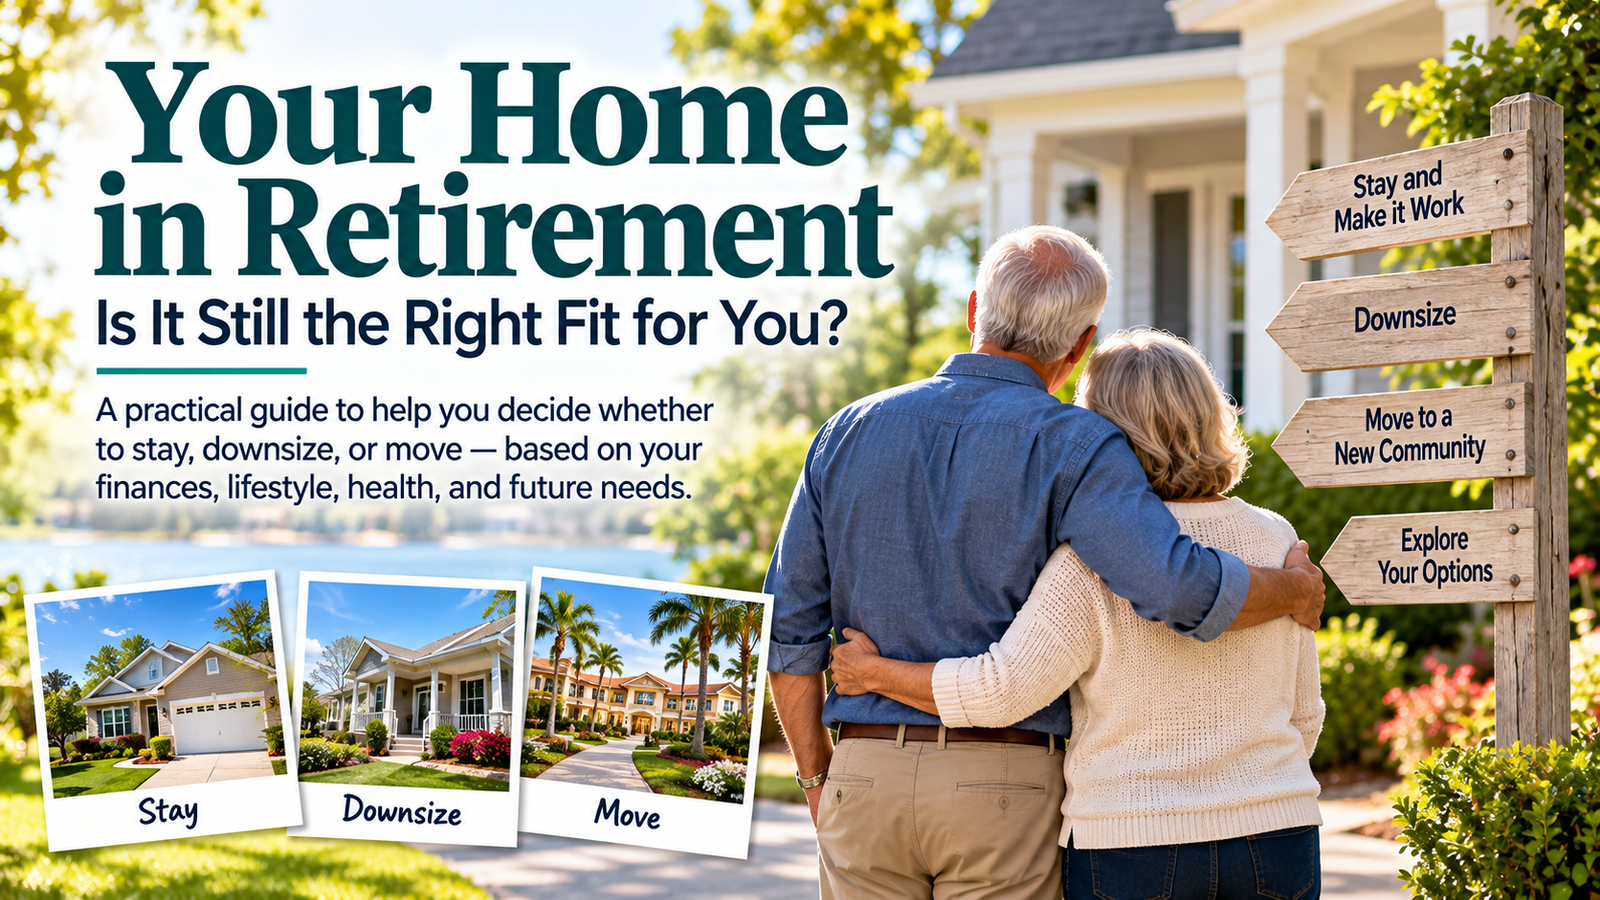
Your home in retirement may be one of the biggest factors in whether your money, independence, and everyday life continue to work well. The house that fit your family and lifestyle years ago may still be exactly where you want to be. Or it may slowly be becoming more expensive, harder to maintain, less convenient, or simply more house than you need.
That doesn’t mean you should move. It means your home in retirement deserves the same kind of checkup as your income, savings, and insurance. Start by looking at the complete household picture. Our Money & Income in Retirement guide can help you compare housing costs with the income available to support them.
Start With a Better Question About Your Home in Retirement
Instead of asking, “Should I downsize?” start with a simpler question:
Does my home still work for the life I am living now—and the life I may be living several years from now?
There is no automatic right answer. Staying may be the best choice. Moving may be the best choice. Making a few changes to the home may solve the problem without moving.
What Does Your Home Really Cost You?
A paid-off mortgage does not make a house free. The real cost of a home in retirement includes expenses that continue long after the mortgage is gone. Add up:
- Property taxes
- Homeowners insurance
- Flood or other special insurance
- Utilities
- HOA or community fees
- Lawn and pool care
- Pest control
- Routine maintenance
- Major repairs such as a roof, air conditioner, plumbing, or appliances
Then look at those costs as part of your retirement income—not as separate bills that somehow do not count. A home can be comfortable and familiar while still taking too large a share of your available monthly income.
Can You Still Manage the Home Comfortably?
Money is only one part of the decision. Think about what it takes to live there every week.
Are you comfortable with stairs? Can you carry groceries from the car to the kitchen? Is the bathroom easy to use? Can you keep up with the yard? If something breaks, do you know who to call? Are there tasks your spouse or partner always handled that would become difficult to manage alone?
These are not reasons to leave your home. They are reasons to identify what may need to change.
Could Small Changes Make Staying Easier?
Sometimes the answer is not a new home. It is a safer and easier version of the home you already have.
Simple changes can include better lighting, sturdy handrails, grab bars, lever-style door handles, non-slip surfaces, easier entryways, or moving frequently used items to make them easier to reach. Larger projects might include a walk-in shower, a ramp, a wider doorway, a first-floor bedroom, or other accessibility improvements. The U.S. Department of Housing and Urban Development also provides information on safer, healthier homes.
Before spending heavily, identify the actual problem you are trying to solve. A few targeted changes can sometimes preserve independence without an expensive remodel.
Your Neighborhood Is Part of Your Home in Retirement
A house can still work while the location stops working.
Think about the places you use regularly. How far are you from groceries, doctors, pharmacies, family, friends, recreation, and other services? What happens if driving becomes difficult or you simply decide you no longer want to drive as much?
A less expensive home in retirement that leaves you isolated or dependent on a car may not improve your life. On the other hand, a smaller home near the people and services you use could make everyday life much easier. Transportation should be part of the housing decision, not an afterthought.
What If One Person Is Living There Instead of Two?
A home can feel very different after the death of a spouse or partner. The expenses may not fall nearly as much as household income does. Maintenance responsibilities that two people shared may now fall on one person.
Do not feel pressured to make a major housing decision immediately after a loss. First understand the costs, the work involved, and whether the home still feels manageable. A decision that can safely wait usually deserves time. If this change follows the death of a spouse or partner, see When a Spouse Dies: Financial Steps for the Surviving Partner.
Downsizing Is an Option, Not an Automatic Answer
Moving to a smaller home sounds straightforward: sell the larger house, buy something smaller, reduce expenses, and free up some money.
Sometimes that works beautifully. Sometimes the numbers are surprising.
Before deciding, compare the complete cost of staying with the complete cost of moving. Include the purchase price or rent, current mortgage rates if financing is needed, property taxes, insurance, HOA fees, moving expenses, repairs or improvements needed before selling, and the cost of furnishing or modifying the next home.
A smaller home is not automatically a cheaper home.
What About Renting Instead?
Renting can remove many maintenance responsibilities and may make it easier to move again later. It can also place you closer to transportation, shopping, family, or activities.
But rent can rise, and you give up some control over the property. Compare several years of likely housing costs rather than just this month’s rent against this month’s mortgage payment.
Be Careful About Using Home Equity as Retirement Income
Your home may contain a large portion of your net worth. That can make home equity loans, home equity investments, or reverse mortgages sound attractive. Before considering a reverse mortgage, review the Consumer Financial Protection Bureau’s reverse mortgage guidance. If you are considering another way to tap equity, our Home Equity Investment guide explains another option and its tradeoffs.
These products work differently and can have significant long-term consequences. Do not treat home equity as free money. Understand the fees, repayment requirements, effect on the equity remaining in the home, and what happens if you move or die before signing anything.
Five Questions to Ask Before Making a Housing Decision
- Can I comfortably afford this home on my retirement income?
- Can I safely and realistically maintain it?
- Does this location support the way I live now?
- What would have to change for me to stay here another five or ten years?
- Would moving actually improve my finances or everyday life after all costs are included?
You Do Not Have to Decide Today
A home carries memories, routines, neighbors, comfort, and a sense of independence. That is why a housing decision in retirement should not be reduced to square footage or a calculator.
Start by identifying what is working and what is becoming difficult. Price the problems before assuming you need to move. Look at your home, your neighborhood, your finances, and the support available around you.
The goal is not to live in the smallest or cheapest home possible. The goal is to have a home in retirement that supports the life you want to live. Revisit the question periodically as your finances, mobility, transportation, household, or priorities change.