
You work hard for your money. But if you want to protect your money for the long haul, you need more than a budget and the right investments.
A job loss, a major repair, a scam, an uninsured loss, stolen identity, or one poorly timed decision can undo years of progress faster than you’d think. You can’t eliminate every financial risk. What you can do is make yourself a lot harder to knock off course.
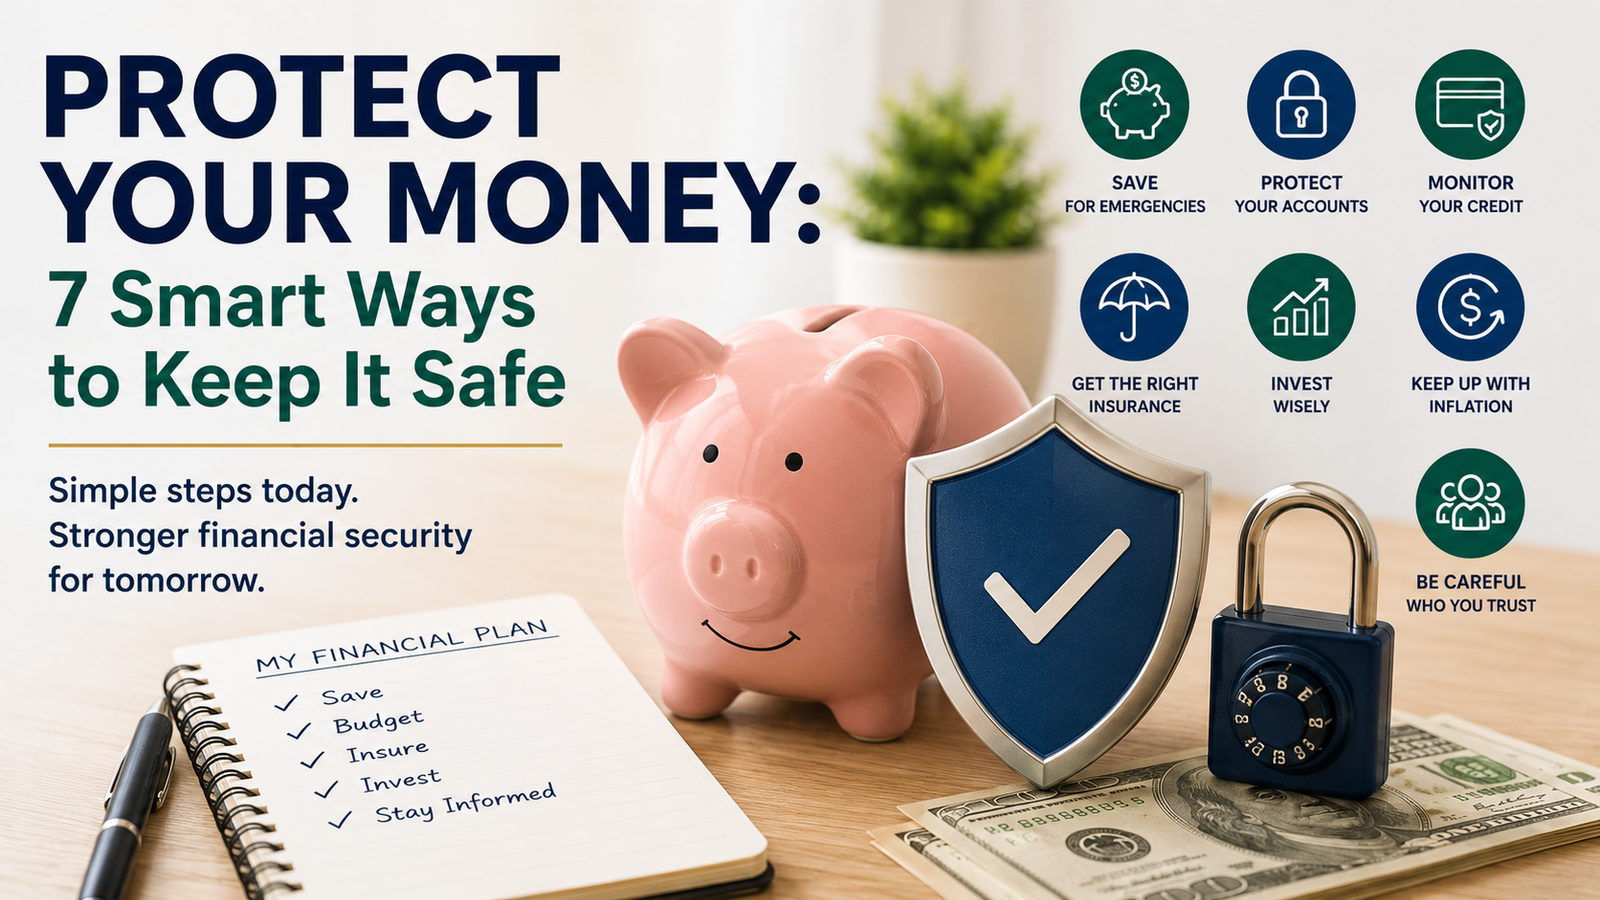
Here are seven practical ways to protect what you’ve built. For the broader concepts behind these safeguards, visit our Financial Education guide.
1. Protect Your Money With an Emergency Fund
One of the simplest ways to protect your money is keeping some of it available for the unexpected. Your car needs a major repair. The air conditioner quits. A medical bill shows up out of nowhere, or your income suddenly drops.
Without savings set aside, an unexpected expense may force you to borrow or postpone another bill. Even a small reserve gives you more options when something goes wrong.
Start with a manageable target. Even $500 or $1,000 can buy you real breathing room. From there, work toward covering several months of essential expenses. The right amount depends on your situation, including how stable your income is, what you’re responsible for, your insurance coverage, and what other resources you have.
Keep this money somewhere safe and accessible, like an FDIC-insured savings account at a bank or a federally insured account at a credit union. The goal isn’t maximum return. It’s having cash there when life doesn’t stick to the plan.
2. Protect Your Money From Scammers
Make account security part of your routine: use unique passwords, enable multifactor authentication, set useful transaction alerts, and keep devices updated.
When an unexpected message asks for money or account access, pause and verify it through a contact method you find independently. For warning signs and the steps to take after a suspicious payment, read Scammers Alert.
3. Protect Your Money by Checking Your Credit
Someone doesn’t need access to your bank account to hurt you financially. They just need enough of your information to open a new account in your name. That’s why protecting your credit is part of how you protect your money.
Check your credit reports periodically for accounts or activity you don’t recognize. You can pull them for free through AnnualCreditReport.com, the federally authorized source for free credit reports.
Consider a free credit freeze with each of the three major bureaus to help prevent new credit accounts being opened in your name. It does not protect existing accounts. Our Scammers Alert guide explains freezes and fraud alerts.
Keep reviewing your account statements as well. A credit report and a bank statement show different parts of your financial activity.
4. Protect Your Money With Insurance That Fits Your Life
Insurance isn’t exciting. Neither is paying thousands of dollars out of pocket because you found out too late your coverage wasn’t what you thought.
Review your policies periodically, especially after any major life change. Depending on your situation, that could mean homeowners or renters insurance, auto insurance, health insurance, life insurance, disability coverage, flood insurance, or umbrella liability coverage.
Don’t focus only on the premium. Look at the deductibles, coverage limits, exclusions, replacement-cost provisions, and what you’d actually owe if something happened. The cheapest policy isn’t necessarily the least expensive one once you actually need to use it.
5. Don’t Put All Your Investment Risk in One Place
If you’re investing for long-term goals, diversification helps manage the risk. The idea is simple: don’t let your financial future ride on one company, one investment, or one type of asset.
Diversification doesn’t guarantee a profit or prevent a loss. What it can do is limit the damage one bad-performing investment does to your whole portfolio. Your mix should reflect your goals, your time horizon, your situation, and how much risk you’re actually willing and able to take on.
This matters more the closer you get to needing the money. Someone investing for retirement 30 years out is in a very different spot than someone planning to start withdrawing next year. Build around your plan, not whatever’s trending online.
6. Protect Your Purchasing Power
Inflation reduces what your money can buy. If something costs $100 today and $120 later, the $100 in your account still has its dollar value, but it no longer buys the same item.
That doesn’t mean every dollar belongs in the market. Money you need for bills, emergencies, and short-term goals has a different job than money meant for something decades away. The key is matching each dollar to its purpose: short-term money usually needs safety and easy access, while long-term money needs room to grow.
There is no single investment that fits everyone’s response to inflation. Start with when you need the money and the risk you can handle. For practical steps involving bills, savings, and retirement, read The Impact of Inflation.
7. Protect Your Money by Limiting Who Has Access
Not every financial threat comes from a stranger. Pressure or misuse can come from someone you know, including a relative, caregiver, acquaintance, or romantic partner. Strong passwords help protect accounts, but they cannot prevent every problem when someone has permission or persuades you to give them access.
Be cautious about adding people to bank accounts, sharing passwords or PINs, giving anyone unrestricted access to your financial records, co-signing loans, signing documents you don’t fully understand, moving money quickly under pressure, or investing because someone you know personally recommended it.
If someone’s pushing you to make a financial decision before you’ve had time to understand it, treat that as a reason to slow down, not speed up. For bigger decisions, get an independent second opinion from a qualified professional who isn’t benefiting from the transaction either way.
Protect Your Money With Systems, Not Worry
You could spend every day worrying about everything that might go wrong financially. That’s not the goal here.
The better approach is putting protections in place before you ever need them: build emergency savings, secure your accounts, watch your credit, keep your insurance current, diversify your long-term investments, think about inflation, and stay careful about who gets access to your financial life.
None of that eliminates risk entirely. Together, though, it makes it a lot less likely that one bad event turns into a full-blown financial disaster.
That’s really what it means to protect your money. You’re not trying to predict everything that could happen. You’re building enough of a buffer that when something does, you’re ready for it.