
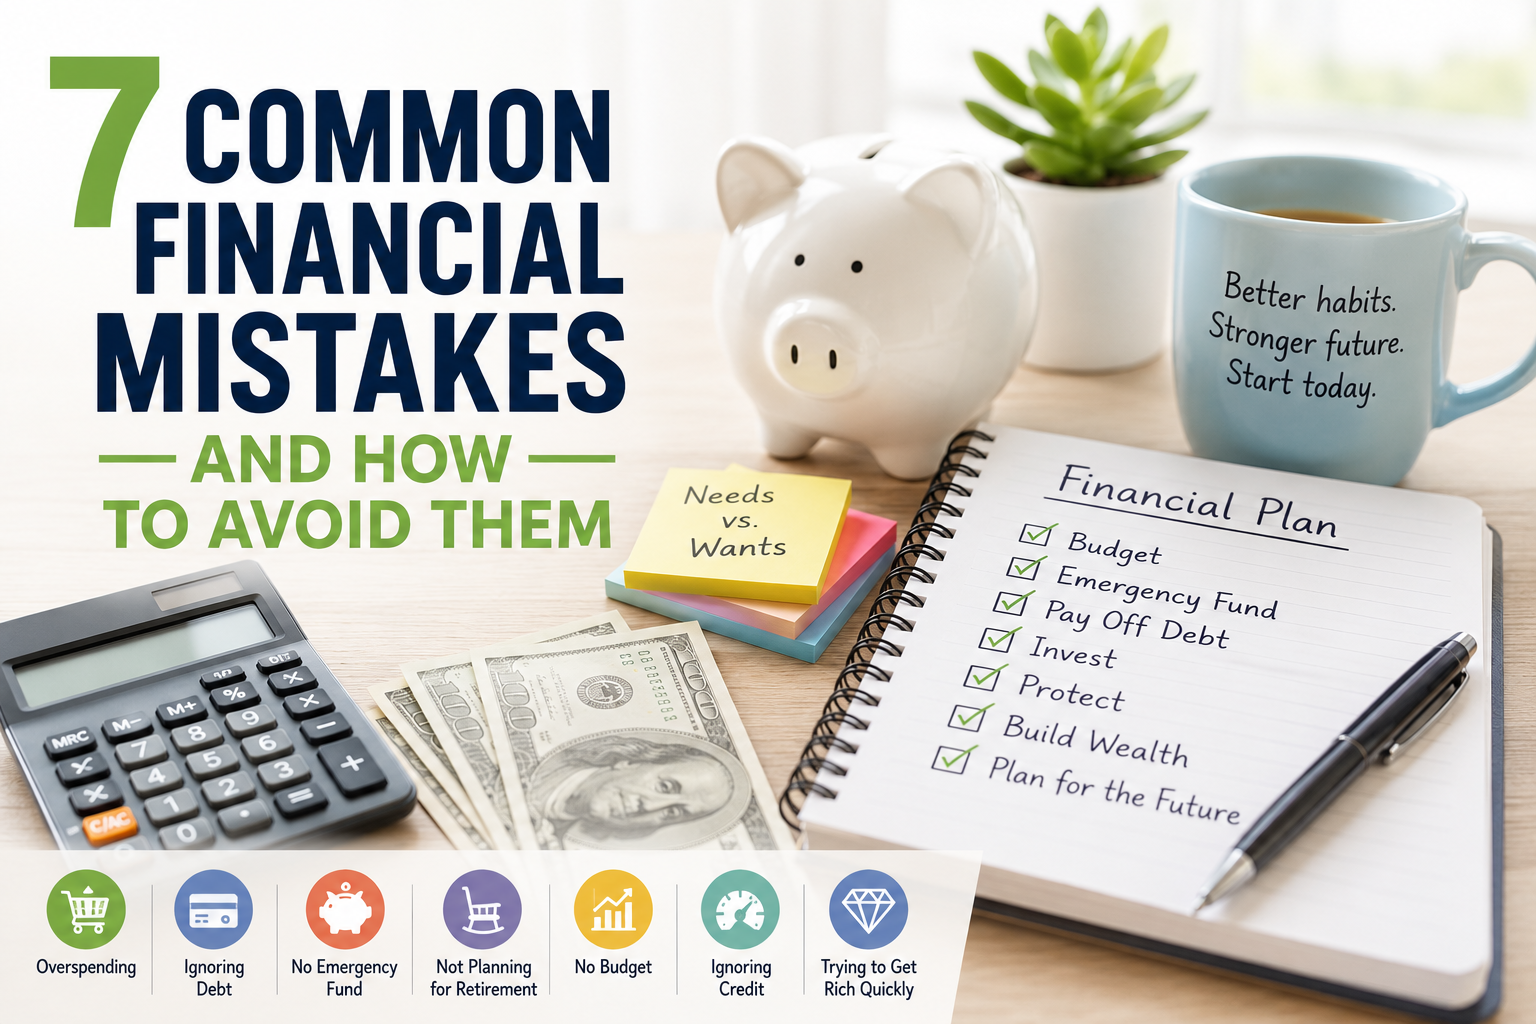
Have you ever looked at your bank account and wondered, “Where did all my money go?” If so, you’ve probably experienced one or more common financial mistakes without even realizing it. Most people don’t get into financial trouble because of one major decision. Instead, it’s usually a series of small habits that quietly chip away at their financial security over time.
Recognizing common financial mistakes helps you choose a useful next step. Some changes are straightforward; others take time, additional income, or outside support. Start with the problem causing the most trouble rather than trying to change everything at once.
Here are seven of the most common financial mistakes—and practical ways to avoid them.
1. Taking On Payments Your Income Cannot Support
A new payment may look manageable on its own while leaving too little for the rest of your household. Before taking on a car payment, installment purchase, or subscription, compare the ongoing cost with your income and existing obligations. If essentials already exceed your income, that is a shortfall to address; it does not automatically mean you have been careless.
How to avoid it:
- Create a realistic monthly budget.
- Track your spending for at least one month.
- Delay non-essential purchases for 24 hours before making a purchase.
- Focus on needs before wants.
Living within your means doesn’t require giving up everything you enjoy. It simply means making intentional decisions with your money.
2. Not Having an Emergency Fund
Unexpected expenses happen to everyone. Car repairs, medical bills, and home repairs don’t wait until your finances are convenient.
Without emergency savings, many people rely on credit cards, creating even more financial stress.
How to avoid it:
- Start by saving $500 to $1,000.
- Gradually build toward three to six months of living expenses.
- Set up automatic transfers into a dedicated savings account.
Even small, consistent contributions add up over time.
3. Ignoring Debt
Debt doesn’t disappear simply because you avoid looking at it. Interest continues to grow, making repayment even harder.
How to avoid it:
- List every debt you owe.
- Make all minimum payments on time.
- Choose either the debt snowball or debt avalanche strategy.
- Avoid adding new debt while paying off existing balances.
The sooner you face your debt, the sooner you can create a plan to eliminate it.
4. Failing to Plan for Retirement
Many people believe retirement is too far away to worry about. Unfortunately, time is one of the most valuable tools investors have.
Waiting even a few years can significantly reduce the growth of your retirement savings.
How to avoid it:
- Contribute to employer-sponsored retirement plans whenever possible.
- Take advantage of employer matching contributions.
- Increase retirement savings gradually whenever your income rises.
Starting small today is almost always better than waiting for the “perfect” time.
5. Planning Monthly Totals but Missing Due Dates
A monthly budget can balance while your checking account runs short before payday. The timing of income, bills, and automatic withdrawals matters as much as the totals.
Use a bill calendar alongside your spending plan. Note when income arrives and when payments leave, including annual renewals. Before making an optional purchase, check what the balance still needs to cover.
How to avoid it:
- Write down each income payment and the date it arrives.
- Put bills, required payments, and renewals on a calendar.
- Check what must be paid before your next income arrives.
- Ask about changing a due date if the timing repeatedly causes trouble.
For help organizing both amounts and timing, read How to Make a Budget That Actually Works for You.
An Example: Enough This Month, Short This Week
Suppose you receive $1,500 on the first and another $1,500 on the fifteenth. Your monthly expenses total $2,800, leaving $200 on paper. But $1,650 in bills and essentials must be paid before the fifteenth. Without money carried over, you are $150 short during the first half of the month.
List the payments due before your next income arrives. You might ask a provider whether a due date can change, reduce optional spending early in the month, or gradually build a cushion for that gap. A changed due date needs the provider’s agreement. Check the new schedule before relying on it. This is a timing problem; taking on a new monthly payment is a separate affordability problem.
6. Ignoring Your Credit
Your credit score can affect borrowing decisions and loan rates. Employment screening is different: employers may review a modified credit report with your written permission, but that report does not include your credit score. State and local rules can restrict employment credit checks. Experian explains what employers can see, and the CFPB explains employment background reports and your rights.
Many people don’t check their credit until something goes wrong.
How to avoid it:
- Pay bills on time.
- Keep credit card balances low.
- Review your credit reports regularly for errors.
- Avoid opening unnecessary accounts.
Good credit is built through consistent habits over time.
7. Trying to Get Rich Quickly
Whether it’s lottery tickets, “guaranteed” investments, or the latest social media trend, quick-money schemes rarely build lasting wealth.
Financial success usually comes from patience and consistency—not shortcuts.
How to avoid it:
- Be skeptical of promises of easy money.
- Focus on long-term investing.
- Continue improving your financial knowledge.
- Build wealth one good habit at a time.
Slow progress often produces the strongest financial foundation.
Why These Financial Mistakes Matter
Every financial decision you make today affects your future. The encouraging news is that none of these mistakes has to define your financial life.
Building good money habits isn’t about perfection. Everyone makes mistakes from time to time. What matters is recognizing them early and making better choices moving forward.
Small improvements repeated month after month often lead to remarkable financial progress.
Final Thoughts
Avoiding these common financial mistakes doesn’t require dramatic changes overnight. Start by choosing one area where you can improve this week. Maybe it’s creating a budget, starting an emergency fund, or finally making a plan to tackle debt.
Financial success is rarely about one perfect decision. It’s built through hundreds of smart choices made consistently over time.
Choose one action for this week: review a proposed payment, put due dates on a calendar, or check a credit report. Our Money Habits: Small Changes That Can Transform Your Life guide explains how to turn that action into a routine you can repeat.
If you want a simple way to start putting these fixes into practice, our free 7-Day Money Habits Challenge walks you through one small step a day.