You’re scrolling your phone when a friend casually mentions they just closed on a second home, and something in your chest tightens before you’ve even finished reading the message. You’ve made responsible choices this year: paid down a card, added to savings, and kept the bills current. Yet for a moment, none of that seems to matter. You feel behind, and that feeling starts to say something about who you are. If you’ve ever felt your stomach drop over someone else’s financial news, you’ve bumped into the tangle between net worth and self-worth, two measurements that have nothing to do with each other, no matter how connected they feel in the moment.
What Net Worth Actually Is
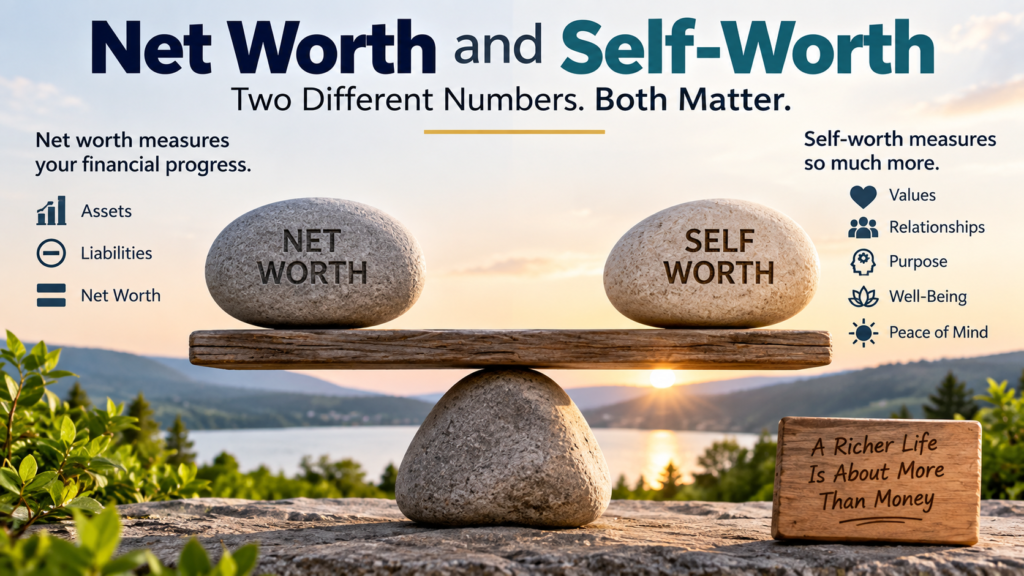
Net worth is nothing more than what you own minus what you owe. Add up your checking and savings, retirement accounts, investments, your home’s value, and anything else worth something, then subtract your mortgage, credit cards, loans, and other debts. If your assets total $200,000 and your debts total $150,000, your net worth is $50,000. If your debts outweigh your assets, the number goes negative, and that might genuinely signal something worth addressing, but it’s a signal, not a verdict on who you are. That’s the entire distinction between net worth and self-worth in a single sentence: one is a math problem, the other never was.
Why the Number Is Actually Useful
Tracking it over time can reveal progress your checking account balance never will. You might feel like nothing’s changing month to month while your mortgage balance quietly shrinks and your retirement account quietly grows. Paying down debt, building savings, avoiding new unnecessary debt—all of it moves the number in a direction worth noticing, even when daily life feels stuck in place. The trouble starts the moment that number becomes a ranking against someone else’s life instead of a measure of your own progress. Confusing net worth with self-worth turns a useful tracking habit into a source of shame.
What the Number Can Never Measure
Net worth says nothing about how you show up for the people you love, what you’ve survived, your honesty, your friendships, your health, or the quiet satisfaction of a life that fits you. Two people can land on the exact same figure and live completely different lives: one exhausted by a demanding job that pays well, the other content with less money but more time and better relationships.
A spreadsheet can’t tell you which one is living better. Money matters; it pays for real things, real needs, real security, but it was never meant to be the score assigned to the person living the life. That’s the whole point of separating net worth and self-worth: one can be calculated, the other can’t.
When a Financial Problem Starts to Feel Personal
Debt and money trouble tend to drag emotions along that never show up on a bank statement: shame, fear, embarrassment, the sense that everyone else figured out something you missed. That reaction is completely human, and it also tends to make things harder to fix, since shame pushes people to avoid statements, delay bills, and skip asking for help, exactly the moments help matters most.
The more useful move is separating the problem from your identity: not “I’m terrible with money,” but “I have credit card debt that needs a plan,” a distinction we lean on heavily in The Minimum Payment Trap. A specific problem has a starting point. A label attached to your whole identity doesn’t. That’s the whole tangle between net worth and self-worth, playing out in real time.
Comparison Distorts Both Numbers at Once
It has never been easier to measure your ordinary life against someone else’s carefully chosen highlight reel, the same trap that shows how social media quietly influences financial decisions. You see the vacation, the new car, the remodeled kitchen. What you don’t see is the monthly payment behind it, the years of saving, the family help, or the stress underneath a life that looks effortless from the outside.
Someone genuinely having more money doesn’t make them worth more; it just reflects their own particular mix of income, timing, decisions, and luck, not a standard you quietly failed to meet. A far more useful comparison is your habits now against your habits a year ago. Chasing someone else’s number is how net worth and self-worth get tangled together in the first place.
The Wealth That Never Shows Up on a Statement
Plenty of what makes life genuinely good never converts into dollars: time you control, good health, real relationships, a skill that saves you money, a friend who shows up during a hard month. None of it appears in a net worth calculation, and all of it affects how well you actually live and how quickly you recover when something financial goes wrong. The Consumer Financial Protection Bureau frames this same idea as financial well-being: the sense of security and freedom money is supposed to provide, not just the number sitting on a balance sheet. Financial wealth is real. It just isn’t the only kind you have.
Using the Number Without Letting It Judge You
A healthy approach looks simple: calculate the number honestly, notice what’s changed, pick one thing you can improve, check back periodically, and stop comparing your figure to anyone else’s. If the number is lower than you hoped, the useful question isn’t what that says about you; it’s what single action moves it in the right direction: an extra payment, a starter emergency fund, one unused expense trimmed. Your next move matters more than your current ranking, and building that kind of steady momentum is exactly what our free 7-Day Money Habits Challenge is built to help with.
Net Worth and Self-Worth Aren’t the Same Thing
Net worth asks what your financial position is right now. Self-worth asks something no balance sheet was ever built to calculate. You can make a bad financial decision and still learn from it, carry debt and still have a real plan to repay it, start saving later than you wanted, and still change your future from here. None of that touches your value as a parent, a friend, a neighbor, or simply yourself. Measure your finances so you can improve them. Just don’t let that measurement decide what you’re worth. Your financial position is one chapter. It was never the whole book.