
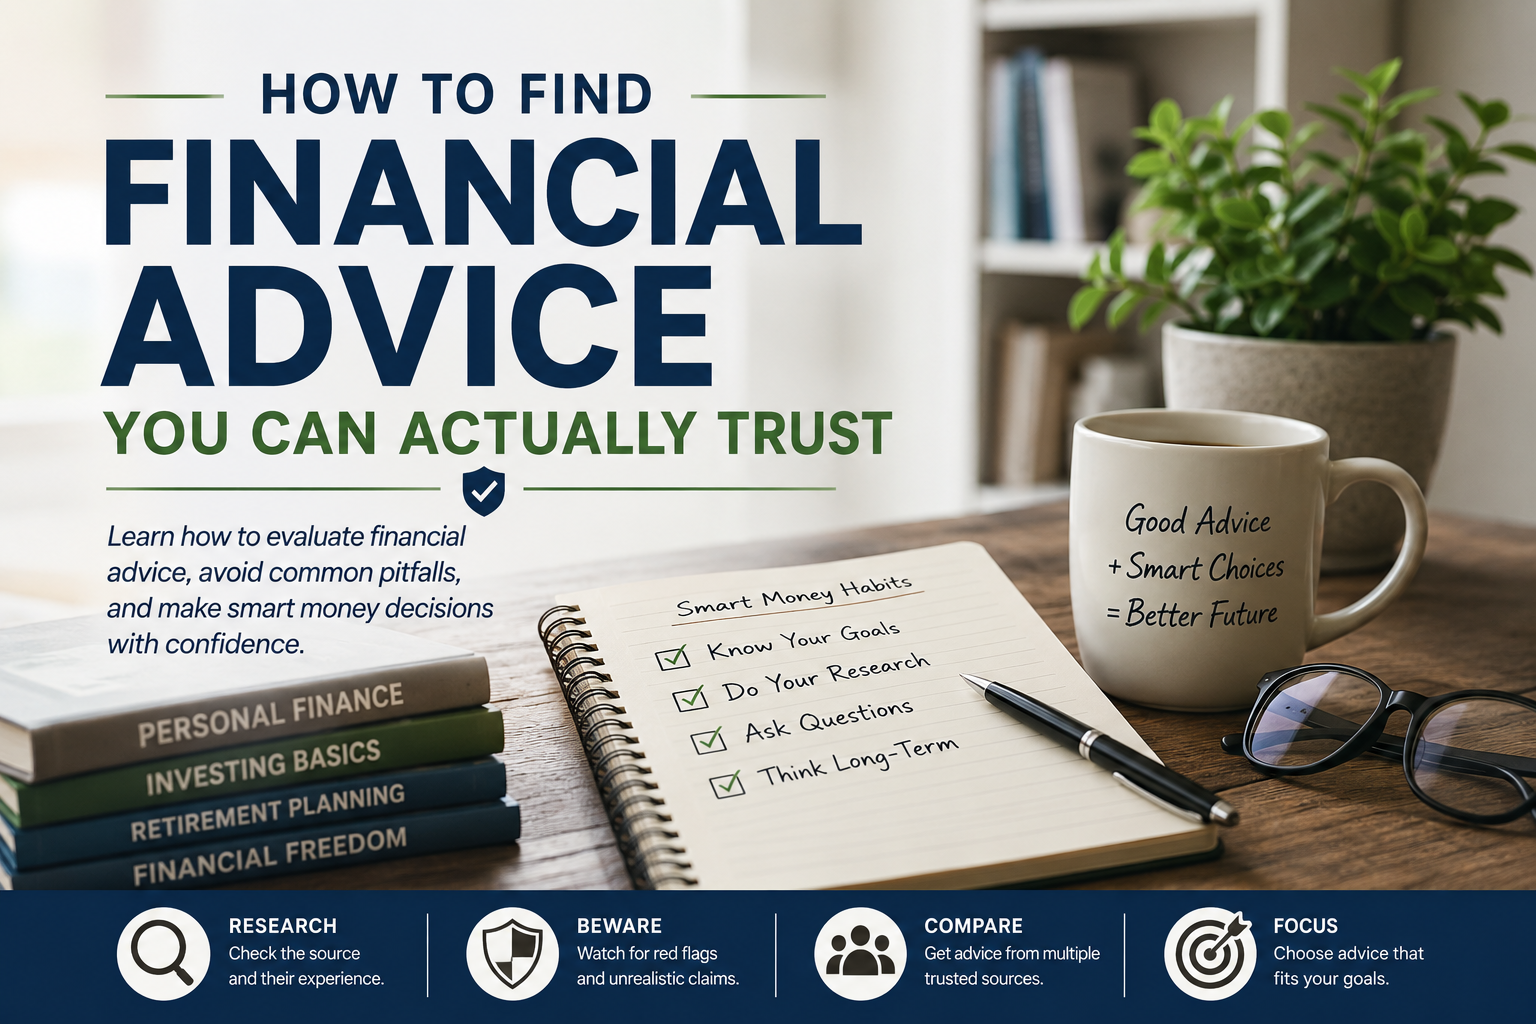
The internet has made financial advice easier to find than ever before. Unfortunately, it has also made it harder to know who to believe. From social media influencers and YouTube personalities to financial advisors and investment firms, everyone seems to have an opinion about the “best” way to manage your money.
The truth is that there is no one-size-fits-all financial strategy. What works for one person may not work for another. Learning how to evaluate financial advice is just as important as the advice itself. For a plain-language introduction to the concepts behind those decisions, visit our Financial Education guide.
Start with Your Financial Goals
Before following anyone’s recommendations, take a step back and ask yourself what you’re trying to accomplish.
Are you trying to:
- Pay off debt?
- Build an emergency fund?
- Save for retirement?
- Buy a home?
- Start investing?
- Improve your credit score?
The best financial advice is the advice that helps you reach your goals—not someone else’s.
Look for Experience, Not Just Popularity
A large following on social media doesn’t automatically make someone a financial expert.
When evaluating a source of financial advice, consider questions such as:
- What experience do they have?
- Do they explain why their recommendations work?
- Are they educating people or simply trying to sell something?
- Do they acknowledge that different financial situations require different solutions?
Trustworthy educators focus on helping people understand financial concepts instead of promising quick riches or guaranteed success.
Be Careful of “One-Size-Fits-All” Advice
You’ll often hear statements like:
- “Everyone should buy real estate.”
- “Credit cards are always bad.”
- “You should never finance a car.”
- “This investment can’t lose.”
Financial decisions are rarely that simple.
Your income, family situation, debt level, age, career, and financial goals all influence what makes sense for you. Good financial advice recognizes that personal finance is exactly that—personal.
Learn From Multiple Trusted Sources
Some financial educators specialize in investing. Others focus on budgeting, debt reduction, retirement planning, or financial independence.
Reading from a variety of reputable sources gives you a broader perspective and helps you recognize common principles instead of following a single personality.
Start with resources you can check directly. Investor.gov explains investing, while the Consumer Financial Protection Bureau’s consumer tools cover topics such as credit, debt, and banking. Compare the reasoning, supporting evidence, and publication dates. Agreement between several sources is useful, but repeating the same claim does not make it true.
Use Financial Institutions as Educational Resources
Many banks, credit unions, brokerages, and investment companies publish free educational articles, calculators, videos, and retirement planning tools.
These resources can help you learn the basics of budgeting, investing, credit, and saving. Just remember that financial institutions also offer products and services, so it’s wise to compare information from several reputable sources before making important financial decisions.
Watch for Red Flags
Some financial advice should raise immediate concerns.
Be cautious if someone:
- Promises guaranteed investment returns.
- Claims you’ll become wealthy quickly.
- Pressures you to act immediately.
- Says their strategy works for everyone.
- Focuses more on selling a product than educating you.
- Encourages borrowing money to invest.
- Uses fear or hype instead of facts.
Building wealth takes time, discipline, and consistent money habits. Anyone promising shortcuts deserves extra scrutiny.
Verify Financial Advice and Professional Credentials
Whenever possible, confirm important financial information through multiple reliable sources. General money education can help you understand your options; personalized financial advice should consider your circumstances. If you are hiring someone, check their background as well as the recommendation.
Use Investor.gov’s investment professional search to check registration and available background information. It connects readers to investment adviser records and, where appropriate, FINRA’s BrokerCheck for brokers. If someone claims CFP® certification, verify it through CFP Board’s verification tool, including its public disciplinary information.
Match the person’s name and firm carefully. These tools check particular registrations or credentials; they do not cover every kind of financial educator or guarantee good advice. Read any disclosures in context, and ask about anything you do not understand.
Ask How the Person Gets Paid
Before paying for financial advice, ask for a written explanation of the services, total costs, and how the professional is compensated. Do they charge an hourly rate, a flat fee, a percentage of investments managed, commissions, or a combination? If a fee is quoted as a percentage, ask what it means in dollars.
For example, 1% of a $100,000 portfolio is about $1,000 a year, before any separate investment costs. Ask whether they receive payments for recommending particular products or referring you elsewhere. A commission does not automatically make advice bad, but it is an incentive worth understanding.
Ask, “Will you act as a fiduciary when providing this service?” In plain language, that means a duty to put your interests first. Get the answer in writing and clarify which services it covers. For applicable investment firms, request Form CRS, the client relationship summary, which outlines services, costs, conflicts, and other important information.
A useful final question is, “What are my alternatives, including doing nothing for now?” Trustworthy financial advice should leave room for questions and time to think.
Build Knowledge Instead of Following Personalities
One of the best ways to improve your financial future is to understand the basic principles of personal finance.
When you understand topics like budgeting, debt management, investing, taxes, insurance, and retirement planning, you’ll be able to evaluate new advice with confidence instead of relying on someone else to make decisions for you.
The goal isn’t to find a financial guru. It’s to become informed enough to recognize good advice when you see it.
Final Thoughts
There are many trustworthy people and organizations willing to help you improve your finances, but no single expert has all the answers. The best financial advice is honest, balanced, supported by sound principles, and appropriate for your personal situation.
As you continue building better money habits, focus on learning, asking questions, and making informed decisions. Over time, you’ll develop the confidence to separate helpful guidance from empty promises—and that’s a skill that will benefit you for the rest of your financial life.