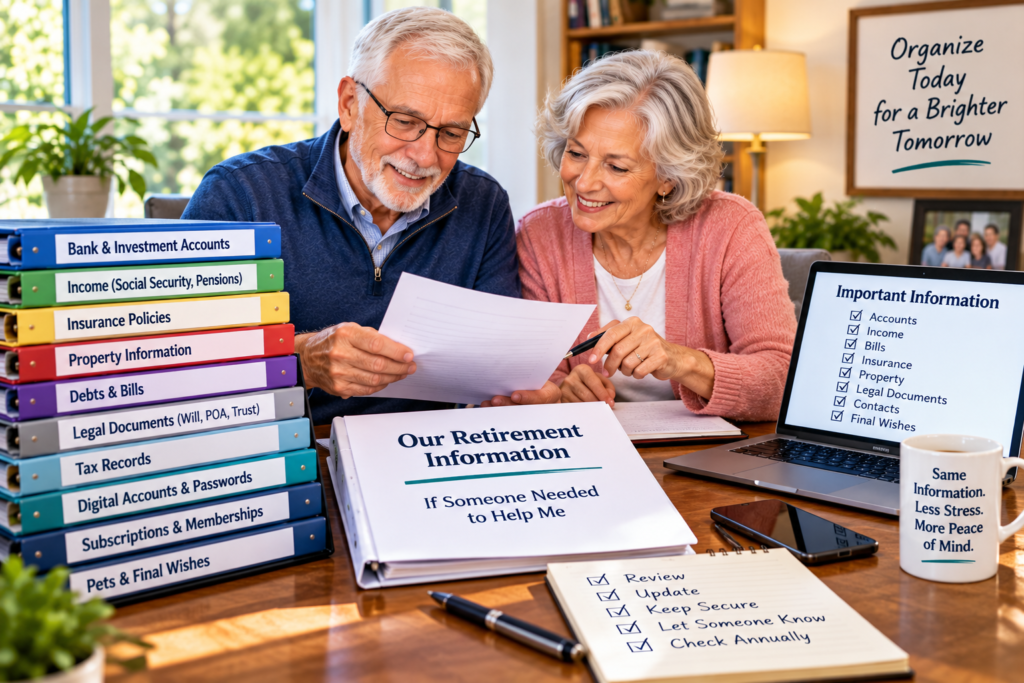
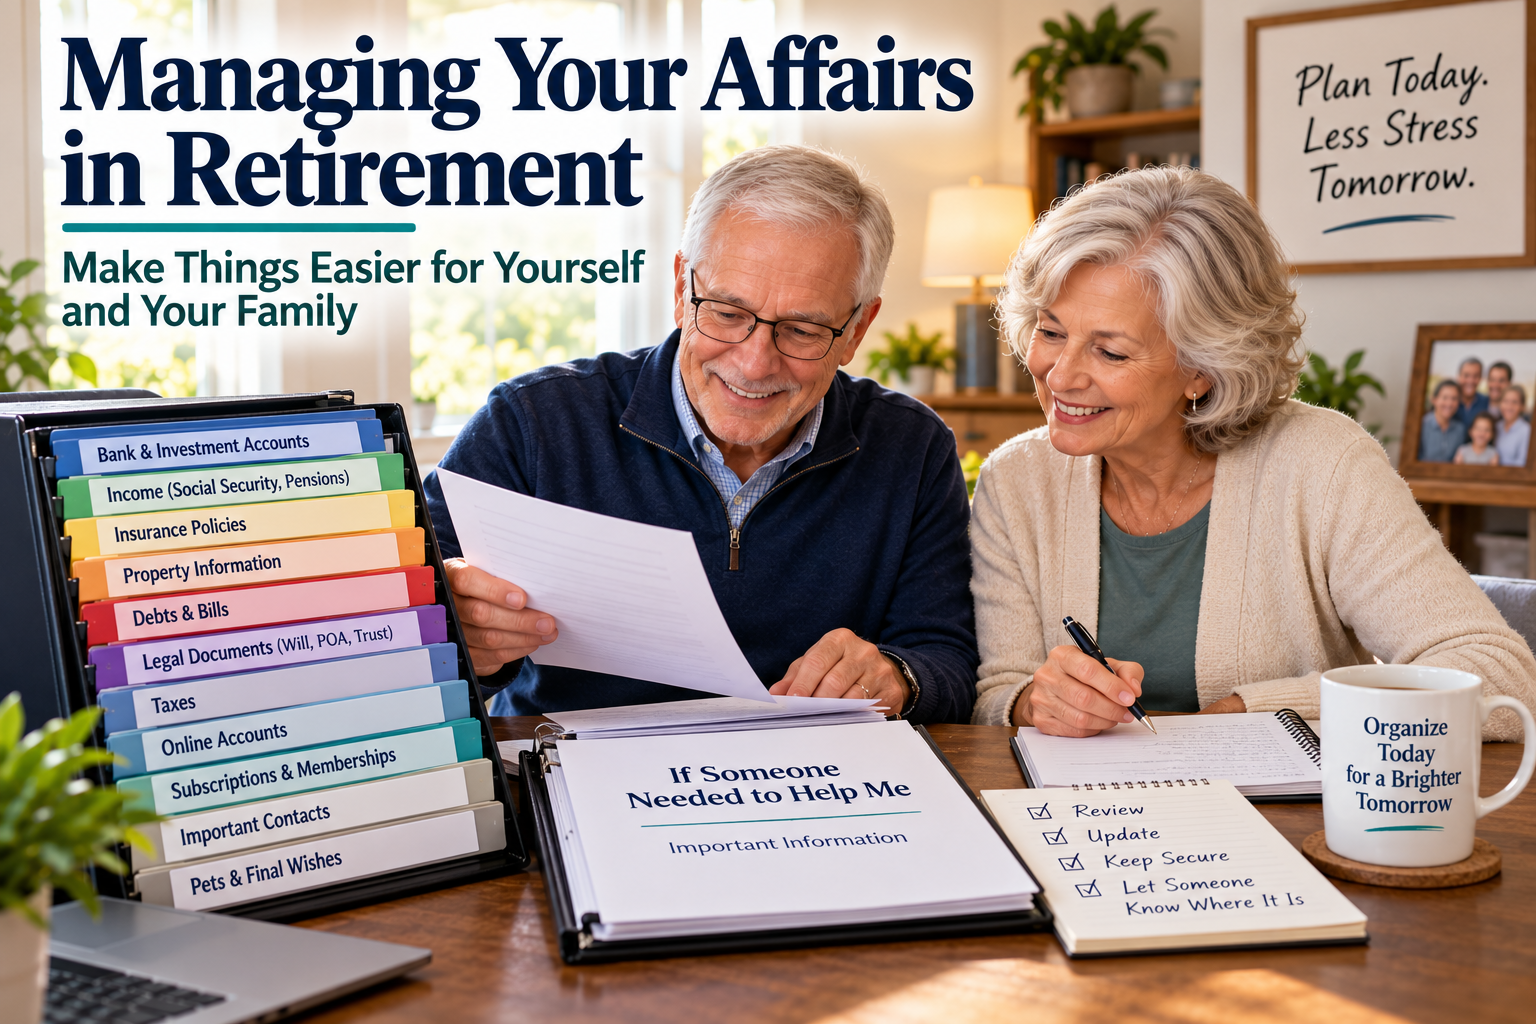
Managing your affairs in retirement is not about giving up control. It is about organizing the important parts of your financial and household life so you can find what you need—and so someone you trust could help if you ever needed them to.
You may know exactly which bank holds your checking account, when the insurance bill is due, where the deed is stored and who manages your pension. But would your spouse, partner or another trusted person know where to begin if you were temporarily unable to handle those things yourself?
The goal is not to create a giant binder full of private account numbers and passwords. Start by creating a simple roadmap.
Managing Your Affairs in Retirement Starts With a Roadmap
Create an “If Someone Needed to Help Me” file. It can be a paper folder, a secure digital document or a combination of both.
The file does not need to contain every confidential detail. It should tell a trusted person what exists, where important information is kept and whom to contact.
Think of it as a table of contents for your financial and household life.
List Your Bank and Investment Relationships
Start with a simple list of financial institutions where you have accounts. Include checking, savings, certificates of deposit, brokerage accounts, IRAs and other investment or retirement accounts.
You do not necessarily need to put full account numbers in an unsecured file. The institution name, type of account and where the detailed records are stored may be enough for your roadmap.
Review beneficiary designations on retirement and investment accounts periodically, particularly after a marriage, divorce, death or other major family change.
Document Where Retirement Income Comes From
Managing your affairs in retirement also means making your income understandable to someone besides you.
List the sources that regularly put money into the household: Social Security, pensions, annuities, retirement-account withdrawals, rental income or other recurring income.
For pensions, include the plan or employer name and contact information. For Social Security, someone helping you should at least know that the benefit exists and where deposits normally appear.
Our Money & Income in Retirement guide can help you review how those income sources support regular household expenses.
Make a List of Regular Bills
Imagine someone had to keep your household running for the next 30 days. What would they need to know?
List the regular bills: mortgage or rent, utilities, insurance, credit cards, loans, HOA fees, phone, internet, subscriptions and other recurring expenses.
Mark which bills are paid automatically and from which account. This can prevent someone from accidentally paying an automatic bill twice—or closing an account that is still paying important expenses.
Organize Insurance Information
Make a list of the insurance policies that protect you and your household. Depending on your situation, that might include homeowners or renters insurance, auto insurance, life insurance, umbrella coverage and other policies.
Record the insurer, type of policy, agent or contact number and where the actual policy information is kept.
If you have life insurance, make sure someone knows the policy exists. Our Whole and Term Life Insurance guide explains the basic differences between common types of coverage.
Keep Property Information Together
For your home or other real estate, identify where deeds, mortgage information, property-tax records, homeowners insurance and HOA information are stored.
If you own rental property, include information about the tenant, lease, property manager if there is one, insurance, mortgage and regular property expenses.
If you are reviewing whether your current home still works for your retirement, see our Home in Retirement guide.
List Debts Without Hiding From Them
Include mortgages, vehicle loans, personal loans, credit cards and other debts. Record the lender or creditor and where statements can be found.
The purpose is not to create a depressing list. It is to make sure obligations do not disappear from view simply because the person who normally handles them is unavailable.
Know Where Tax Records Are Stored
Keep recent tax returns and supporting records organized enough that they can be located when needed. Include the name and contact information of your tax preparer if you use one.
You do not need decades of random paperwork scattered throughout the house. Follow current record-retention guidance appropriate to your circumstances and securely destroy documents you no longer need.
The IRS provides general guidance on how long different tax records should be kept.
Wills, Trusts and Powers of Attorney Need More Than a Drawer
Legal documents are only useful if the right people know they exist and can locate them when needed.
Know where your will, trust documents and powers of attorney are stored. Make sure the people named in important roles know that they have been named and know how the documents can be accessed when appropriate.
Our Estate Planning Guide covers the broader planning process, while Estate Planning 101 provides an approachable introduction to wills, trusts and related decisions.
Estate laws and legal-document requirements vary by state and individual circumstances. An estate-planning attorney can explain how those rules apply to your situation.
Review Beneficiaries Separately From Your Will
Do not assume your will controls every financial account.
Retirement accounts, life insurance policies and certain other assets may pass according to beneficiary designations or ownership arrangements. Review those designations periodically and after major life changes.
If you are unsure how a beneficiary designation interacts with your estate plan, ask the financial institution and your estate-planning professional rather than guessing.
Managing Your Affairs in Retirement Includes Your Digital Life
More of our lives now exist online: banking, investments, utilities, shopping accounts, social media, cloud photo storage, email and subscriptions.
Create a list of important digital accounts and decide how trusted people could identify or manage them if necessary. Do not leave an unprotected sheet of passwords sitting beside your computer.
A reputable password manager or another secure method can reduce the need to maintain multiple exposed password lists. Whatever method you use, someone you trust should know that the system exists and how appropriate access would be handled.
Review Subscriptions and Memberships
Streaming services, software, clubs, publications, storage services and other subscriptions can quietly continue charging a credit card or bank account.
Keep a simple list of recurring subscriptions and memberships. This makes them easier for you to review now and easier for someone else to cancel later if necessary.
Include Professional Contacts
List the people who help you with important financial or legal matters. That might include an attorney, accountant, financial professional, insurance agent, property manager or other adviser.
A trusted family member does not need to know everything those professionals know. They need to know whom to call.
Our Financial Support Network guide explains the different types of people who may help with financial decisions.
Do Not Forget Pets and Everyday Responsibilities
Managing your affairs in retirement is not only about money and legal documents.
If you have pets, someone should know who could care for them and where veterinarian and medication information is kept. If there are household routines another person would not know—such as pool service, lawn care, pest control or a security system—include enough information to keep those services functioning.
Final Wishes Can Reduce Guesswork
There may be personal preferences you want your family to know that do not belong in a bank statement or investment account.
Write them down and tell someone where the information is kept. The purpose is not to plan every detail of the future. It is to reduce unnecessary guessing during a difficult time.
Keep Sensitive Information Secure
Organization should not create a security problem.
Do not place full account numbers, Social Security numbers, PINs and passwords in an obvious binder labeled “Everything You Need to Know.” Separate the roadmap from highly sensitive information and use appropriate physical or digital security.
Be especially cautious about giving someone financial access simply because they occasionally help you. Our Elder Financial Abuse guide explains why maintaining reasonable boundaries matters.
Tell Someone Where the Roadmap Is
The best-organized information in the world is not useful if nobody knows it exists.
Choose at least one trusted person and tell them where your “If Someone Needed to Help Me” information is kept. Explain what it contains and what it does not contain.
That conversation does not give the person authority over your finances. It simply prevents them from starting from zero if you ever need help.
Review Your Affairs Once a Year
Managing your affairs in retirement is not a one-time project. Accounts close. Banks merge. Insurance changes. People move. Beneficiaries change. Password systems change. Professionals retire.
Once a year, spend an hour reviewing your roadmap. Cross out what no longer applies, add what is new and make sure contact information is current.
If something major changes during the year—a death, divorce, move, new account, property sale or major financial change—update the information then rather than waiting.
Connect Your Plan With Your Support Network
Your organized affairs and your support network should work together.
Our Support Network in Retirement guide helps identify who could assist with transportation, home access, pets, emergencies and everyday problems without automatically giving those people control over your finances.
Managing Your Affairs in Retirement Is a Gift to Yourself Too
It is easy to think this work is only for the people who may eventually have to help you. It is not.
Organizing your affairs makes your own life easier. You know where documents are. You can see which accounts exist. You can review beneficiaries. You can spot subscriptions you no longer need. You can find the insurance policy without opening six drawers.
Managing your affairs in retirement means staying organized, staying involved and making sure the people you trust could find the right information if they ever needed to help.
You remain in control. You simply make sure nobody—including you—has to start from scratch when something important needs attention.