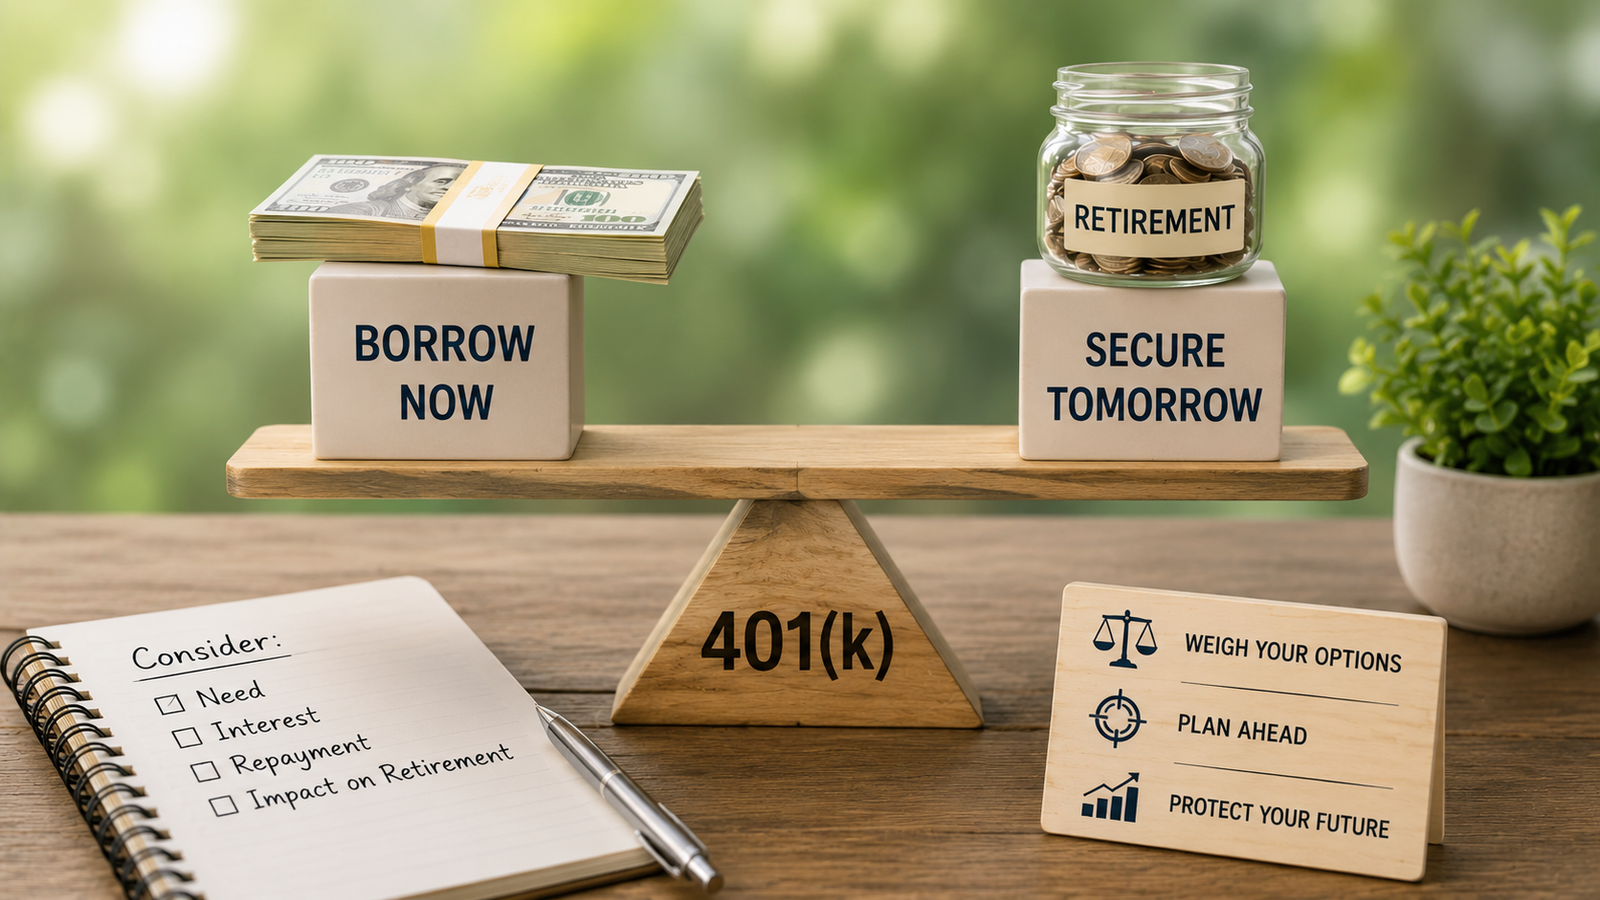
Borrowing from your 401(k) can seem simpler than borrowing from a bank. The money is already there, and you may be able to repay it through payroll. But “borrowing from myself” does not mean the decision has no cost.
The useful question is whether the loan solves the immediate problem without creating a repayment problem or weakening your retirement plan. Start with the actual terms, your take-home pay, and what would happen if your job changed.
Photo by Kelly Sikkema on Unsplash.
A 401(k) Loan Is Different from a Withdrawal
A plan loan must be repaid under its terms. A qualifying loan is not initially treated as a taxable distribution. A hardship withdrawal is a separate transaction with different eligibility and tax rules; it is not a loan you simply repay. The IRS overview of loans and withdrawals explains that distinction.
Before borrowing from your 401(k), confirm that the plan offers loans. Do not assume that another employer’s policy—or an online example—applies to your account. IRAs do not permit participant loans.
What Your Plan May Allow
The IRS loan FAQs describe a general maximum of the lesser of $50,000 or 50% of the vested balance, with a permitted small-balance exception. Existing and recent loans can reduce availability; your plan can impose lower limits.
Most loans require repayment within five years through substantially equal principal-and-interest payments at least quarterly. A principal-residence purchase loan may allow longer. Get the actual schedule, interest rate, fees, and payment method from the administrator.
The permitted maximum is not an affordability recommendation. Borrowing from your 401(k) should begin with the amount you need and can repay, rather than the largest number on the application screen.
A Simple Repayment Example
Suppose you borrow $10,000 at a hypothetical fixed annual interest rate of 8%, repaid over five years in 60 equal monthly payments. With monthly amortization and no fees, the payment is approximately $202.76, with a small rounding adjustment to the final payment.
| Illustrative loan item | Amount |
|---|---|
| Amount borrowed | $10,000 |
| Monthly payment | About $202.76 |
| Total principal and interest repaid | About $12,165.84 |
| Interest within that total | About $2,165.84 |
This is a calculation, not a current plan quote. Payroll timing, fees, and your plan’s terms may produce different payments. Ask how much spendable pay you would have after the deduction, and put that figure into your household budget.
Then test an ordinary difficult month: a car repair, a higher utility bill, or fewer paid hours. If the payment would force you to borrow elsewhere for necessities, the original loan has not solved the whole problem.
Interest Paid to Your Account Is Not Free Money
With a plan loan, interest generally goes back into your retirement account. But it comes from your household cash flow. It is not an outside investment return someone else is paying you.
The borrowed portion is no longer in its previous investments. The money still invested can rise or fall, and repaid amounts return over time. The overall result depends partly on market performance, interest, fees, and changes to contributions.
If markets rise, you may miss gains on the borrowed amount. If markets fall, that comparison can look different. Neither outcome is known in advance. Borrowing from your 401(k) should not become an attempt to predict the market.
Loan repayments are not retirement contributions. If repayments squeeze out regular contributions, you may also lose employer matching money under your plan’s rules. Compare both lines on your pay statement instead of assuming that paying back the loan keeps the original savings plan intact.
What Happens If You Leave Your Job?
Before borrowing from your 401(k), ask whether payments can continue after resignation, retirement, or a layoff. Plan terms differ. Get the deadlines and procedures in writing rather than assuming either immediate repayment or unlimited time.
A plan loan offset occurs when the plan reduces your account balance to settle the unpaid loan. Certain qualified offsets connected with employment separation or plan termination can be rolled over using replacement money by the federal tax-return due date, including extensions, for the offset year.
That rollover window is not extra time to continue the original loan payments. You need money from other resources to make the eligible rollover. An ordinary missed-payment deemed distribution is different and is not eligible for rollover.
Ask the administrator and a qualified tax professional which situation applies. Previously untaxed amounts can become taxable, and an additional early-distribution tax may apply depending on age and exceptions. Do not wait until filing season to investigate a missed payment or offset notice.
Compare the Options You Actually Have
Borrowing from your 401(k) may compare favorably with a very expensive alternative, but compare written terms rather than an appealing slogan. Include fees, required payments, retirement effects, and job uncertainty.
- Could a provider offer an affordable payment arrangement?
- Could accessible savings cover part of the expense while leaving a reasonable cushion?
- What are the actual APR, fees, and repayment terms of an available personal loan?
- If the issue is recurring debt, would nonprofit credit counseling help address the underlying shortfall?
A lower quoted interest rate does not automatically mean a better overall choice. Equally, a retirement loan is not automatically wrong in every circumstance. The comparison should reflect what is available, affordable, and sustainable for your household.
If borrowing from your 401(k) would pay off credit cards, decide what prevents the balances from returning. Otherwise, you could end up with both the retirement loan deduction and new card payments.
Questions for the Plan Administrator
- How much can I borrow after accounting for existing and recent loans?
- What are the interest rate, setup fee, ongoing fees, and net proceeds?
- How will payments affect take-home pay, and can I continue regular contributions?
- What happens after a missed payment or a change in employment?
- Can I repay early, and what procedures apply?
Connect the decision to your broader Investing & Wealth plan. If you already feel behind on retirement, compare the effect on that gap rather than looking only at this month’s relief.
Before applying, obtain the repayment schedule and test it against your budget. Borrowing from your 401(k) is a real financial commitment. A useful decision accounts for both the expense you need to pay now and the future income that account is meant to support.